
Nobody wants to think about the day their family has to plan a funeral, settle an estate, or figure out how to pay bills without a breadwinner’s income. But that’s exactly why family heritage insurance exists to make sure love, not money, is what your family remembers most during a hard time.
Family heritage insurance is a broad term for life insurance and supplemental coverage designed to protect a family’s financial legacy: final expenses, outstanding debts, estate taxes, and the wealth you want to pass down to your kids or grandkids. Done right, it turns a moment of grief into a moment of relief.
In this guide, you’ll learn exactly how family heritage insurance works, what it covers, how much you actually need, and how to shop for a policy without getting overwhelmed by jargon or sales pressure.
What Is Family Heritage Insurance and How Does It Work?
Family heritage insurance is a form of life or whole-life coverage built to protect a family’s financial legacy. It pays a death benefit to your beneficiaries, can build cash value over time, and is typically used to cover final expenses, debts, estate taxes, or an inheritance for the next generation.
At its core, the mechanism is simple. You pay a premium monthly, quarterly, or annually and in exchange, the insurer guarantees a payout (the death benefit) to the people or trust you name as beneficiaries. Depending on the policy type, it may also accumulate cash value you can borrow against while you’re alive.
Who tends to use this kind of coverage?
- Parents and grandparents who want to leave something behind besides bills
- Homeowners with a mortgage or other debt that shouldn’t fall on a surviving spouse
- Business owners planning a succession or buy-sell agreement
- Retirees focused on covering final expenses so kids aren’t left scrambling
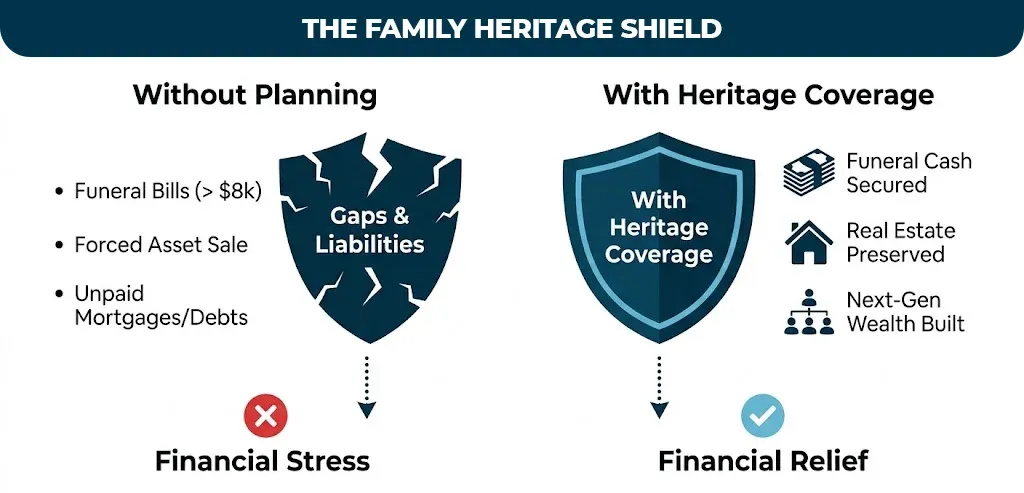
The financial stakes are real: according to LIMRA’s insurance barometer research, a large share of U.S. households say they’d feel a financial hit within a few months of losing a primary wage earner, and roughly 4 in 10 households have no individual life insurance at all. On the expense side, the National Funeral Directors Association has put the median cost of a funeral with viewing and burial well above $8,000, a bill that often lands on the family within days, long before any estate settles.
A quick note on terminology: “family heritage insurance” is used here as a general industry term for legacy-focused life and supplemental coverage. It’s separate from Family Heritage Life Insurance Company of America, a specific insurer now operating as the Globe Life Family Heritage Division; more on that distinction in the FAQ section below.
Key Benefits of Family Heritage Insurance
A well-chosen policy does more than pay out when someone dies. Here’s what it actually accomplishes for a family.
Covers Final Expenses So Grief Doesn’t Come With a Bill
Funeral homes typically expect payment within days. A dedicated final expense or burial policy hands your family cash quickly, without probate delays, so they can focus on each other instead of a spreadsheet.
Preserves the Estate No Fire-Sale of Family Assets
Estate taxes, legal fees, and outstanding debts can force families to sell a home, land, or a business just to cover the bill. A heritage policy provides liquid cash so real assets can stay in the family.
Funds the Next Generation
Whether it’s a grandchild’s education, a child’s first home down payment, or seed money for a family business, the death benefit can be earmarked for the goals that matter most to you.
Peace of Mind That Doesn’t Depend on the Market
Permanent policies lock in a guaranteed benefit and (often) a fixed premium, regardless of what happens to your health or the stock market later in life.
Types of Family Heritage Coverage Options
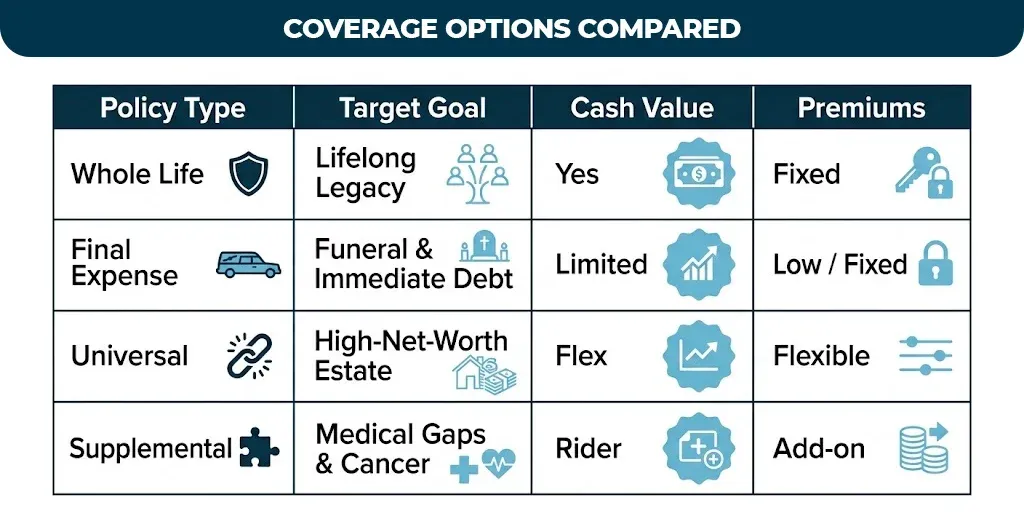
Not all legacy-focused coverage looks the same. Here’s how the main options compare.
| Policy Type | Best For | Premiums | Cash Value? |
| Whole Life / Permanent | Long-term legacy planning, guaranteed lifelong coverage | Fixed for life | Yes grows over time |
| Final Expense / Burial | Covering funeral and immediate debts, smaller face amounts | Fixed, budget-friendly | Limited, slower growth |
| Universal / Estate Protection | High-net-worth estate tax planning, flexible legacies | Flexible, can adjust | Yes flexible growth |
| Supplemental (cancer, accident, hospital) | Filling gaps major medical doesn’t cover | Low, add-on cost | Typically none (unless return-of-premium rider) |
Some supplemental health policies including certain cancer insurance products offer a return-of-premium feature, which refunds a portion of what you paid in if you never file a claim. It’s worth asking any insurer you’re comparing whether that option is available and what it costs.
How Much Family Heritage Coverage Do You Actually Need?
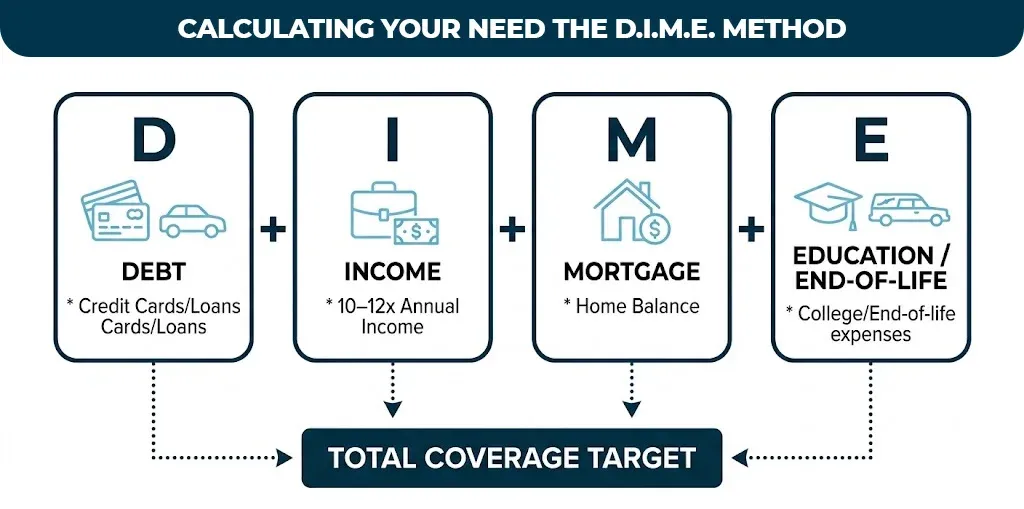
A common starting point is the DIME method: add up Debt, Income replacement, Mortgage balance, and Education/end-of-life expenses. That total gives you a realistic coverage target instead of guessing at a round number.
Break it down like this:
- Debt: Credit cards, car loans, personal loans anything that wouldn’t disappear with you
- Income replacement: Multiply your annual income by the number of years your family would need support (a common rule of thumb is 10–12x annual income)
- Mortgage: The remaining balance on your home
- Education & end-of-life: College costs for kids, plus final expenses (funeral, medical bills, legal fees)
Two more things worth building into the number: inflation, since a benefit set today needs to still be meaningful in 15–20 years, and final-expense costs specifically, since those get paid first and can eat into what’s left for the rest of the family if you don’t account for them separately.
Step-by-Step: How to Buy Family Heritage Insurance
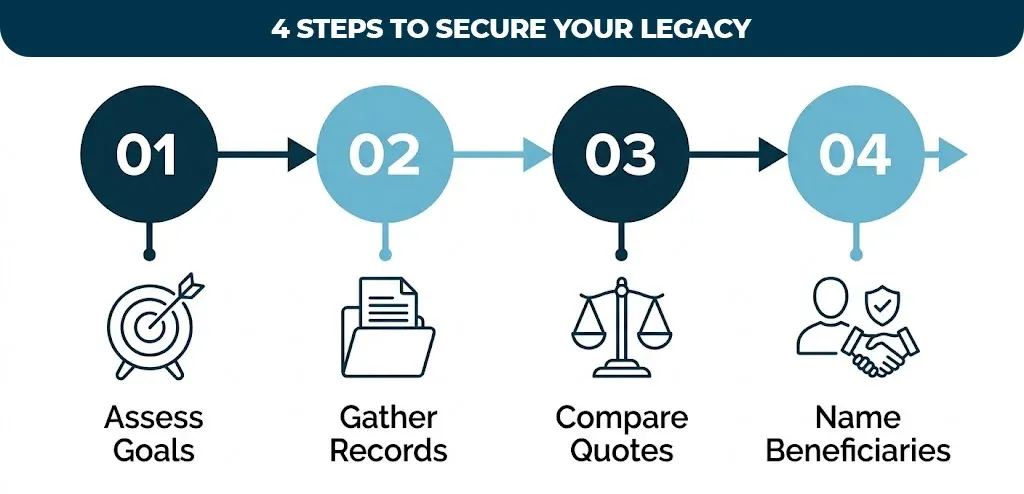
- Assess your family’s goals. Is the priority clearing debt, covering a funeral, or building a multi-generational legacy? Your answer shapes which policy type fits.
- Gather your medical and financial information. Some policies require a medical exam (fully underwritten); others use simplified issues or guaranteed issues with few or no health questions, usually at a higher premium.
- Compare quotes from multiple insurers. Rates for similar coverage can vary significantly between companies, so it pays to compare rather than accept the first offer.
- Name your beneficiaries clearly. List primary and contingent beneficiaries by name (not just “my children”) and consider a trust if your estate is more complex this alone can prevent probate delays.
Final Thoughts: Protecting the People Who Matter Most
Family heritage insurance isn’t about dwelling on worst-case scenarios, it’s about making sure the people you love aren’t left with financial stress on top of everything else. Whether your priority is covering funeral costs, protecting a family home, or leaving something meaningful for the next generation, the right policy turns a hard moment into a manageable one.
If you’re ready to compare final expense and legacy coverage options from top-rated providers side by side, Insure Final Expense can help you find a plan that fits your family and your budget with no obligation to get a free, personalized quote.
Expert Final Expense & Life Insurance Agent
Steffanie is a licensed life insurance specialist at Insure Final Expense, focusing on final expense, burial, and senior life insurance solutions. With years of industry experience, she helps families secure affordable coverage designed to protect their loved ones from financial hardship. Her content is carefully researched, compliance-focused, and created to provide clear, trustworthy guidance so readers can make confident insurance decisions.