
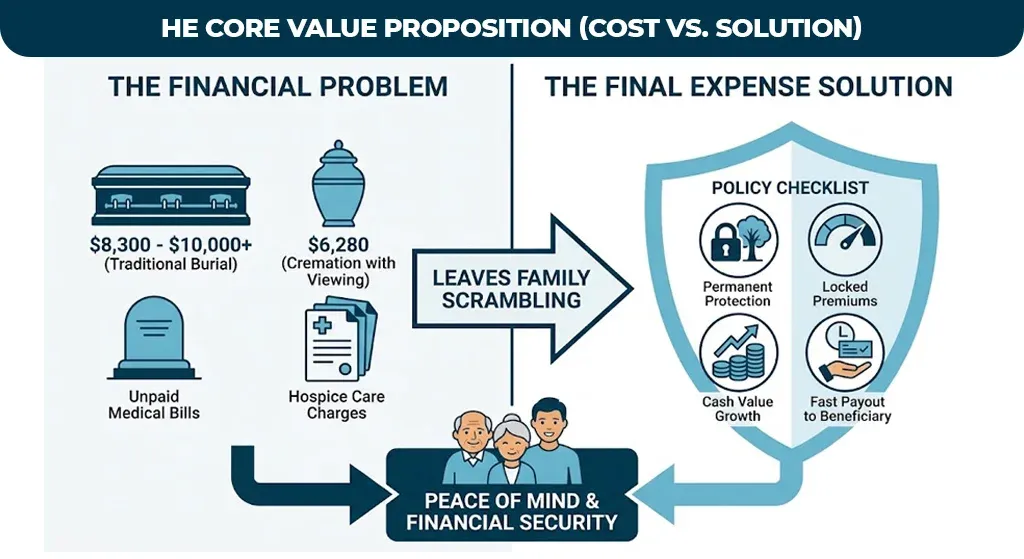
Final expense insurance for seniors is one of the most affordable ways to shield your family from the rising cost of a funeral. The median U.S. funeral now runs between $6,280 for cremation with a viewing and $8,300 to $10,000+ for a traditional burial. Without a plan in place, loved ones are often left scrambling for thousands of dollars during an already painful time.
This guide breaks down how burial insurance for seniors actually works, what it costs at different ages, and how to choose a final expense program that fits your health and your budget without ever sitting through a medical exam.
What Is Final Expense Insurance for Seniors?
Final expense insurance, sometimes called burial insurance, funeral insurance, or final expense life insurance is a specialized type of permanent whole life insurance built specifically to cover end-of-life costs. Unlike large traditional policies designed to replace lost income, a final expense insurance for seniors plan pays a smaller, more manageable amount aimed squarely at funeral, burial, and related bills.
According to the National Association of Insurance Commissioners (NAIC), whole life insurance is a permanent form of coverage that pairs a death benefit with a built-in savings component, and final expense policies follow that same structure on a smaller scale. Most final expense programs offer death benefits between $5,000 and $25,000, though some carriers extend options up to $50,000 for seniors who want a larger cushion for their families.
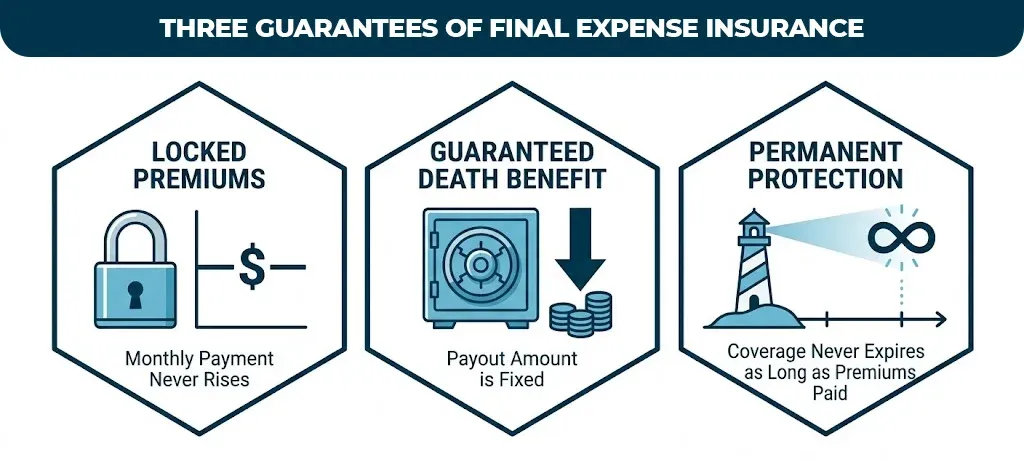
Three guarantees make this type of elderly life insurance especially appealing to retirees:
- Fixed, level premiums your monthly payment is locked in at your approval rate and never rises because of age or a new diagnosis.
- Guaranteed death benefits the payout is set at purchase and can never be reduced later.
- Permanent protection coverage never expires as long as premiums are paid, unlike term life insurance for seniors over 60, which eventually runs out.
Because it’s whole life coverage, a final expense policy also builds cash value over time. A small portion of every premium grows tax-deferred, and many policies let you borrow against that balance if an emergency arises while you’re still living.
Why Seniors Need Final Expense Coverage
Funeral costs have climbed steadily for years, and most families underestimate how many separate charges are involved in a single funeral expense insurance claim, including:
- Casket or cremation container
- Funeral home and director fees
- Embalming, viewing, and visitation costs
- Cemetery plot, vault, and headstone
- Transportation and obituary fees
The National Funeral Directors Association (NFDA) places the median cost of a traditional burial with viewing at roughly $8,300, while cremation with a viewing and service runs closer to $6,280 and both figures keep climbing with inflation.
Beyond the funeral itself, a tax-free lump-sum payout from a burial insurance policy can be used however the beneficiary needs, including:
- Unpaid medical bills, co-pays, or hospice care charges
- Credit card debt, personal loans, or lingering utility balances
- Travel costs for out-of-town family members
- Legal or probate-related fees
One of the most persistent myths is that Social Security automatically covers these costs. In reality, the Social Security Administration’s one-time death benefit is capped at just $255, and it’s only paid to a qualifying spouse or dependent nowhere near enough to offset even a modest cremation. That gap is exactly why a dedicated final expense plan matters.
Types of Final Expense Policies: Simplified vs. Guaranteed Issue
Not every senior qualifies for the same type of policy. Understanding the difference between simplified issue whole life insurance and guaranteed issue final expense coverage is the key to finding the best burial insurance for your situation.
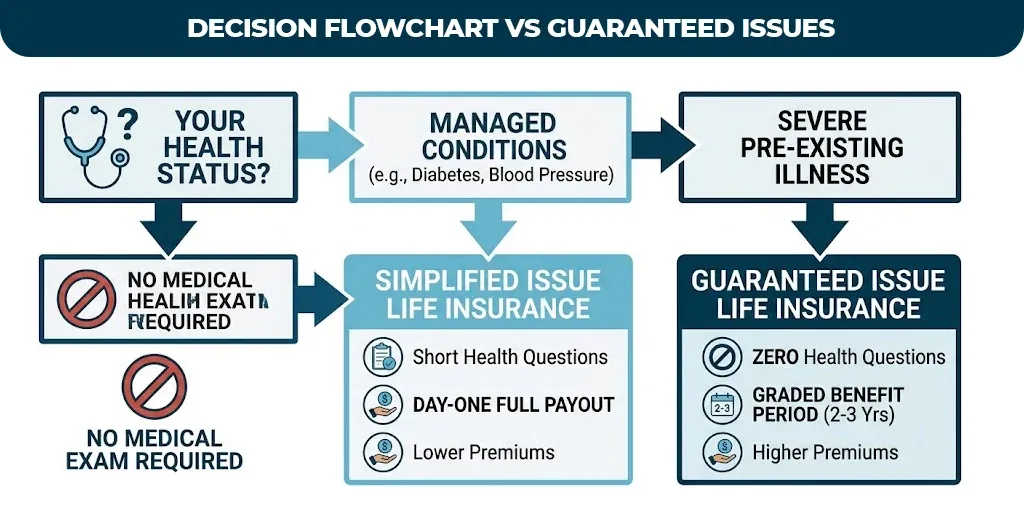
| Policy Feature | Simplified Issue Whole Life | Guaranteed Issue Whole Life |
| Medical Exam Required? | None (no blood tests or physicals) | None |
| Health Questions? | Short list of medical history questions | Zero health questions asked |
| Coverage Effective Date | Day-one full payout for natural & accidental death | 2–3 year graded period for natural death |
| Monthly Cost | Lower premiums for equal coverage | Higher premiums due to higher carrier risk |
| Best Target Audience | Seniors with managed conditions (diabetes, high blood pressure) | Seniors with severe pre-existing illnesses |
Seniors who qualify for simplified issue coverage typically get day-one full benefits for both natural and accidental death, plus lower premiums. Guaranteed issue policies, by contrast, usually apply a two- to three-year graded period: if death from natural causes occurs during that window, most carriers return premiums paid plus roughly 10% interest rather than the full face value. Accidental death is still paid in full from day one on most guaranteed issue plans.
If you specifically want to avoid a waiting period, ask agents directly about burial insurance with no waiting period. Some simplified issue carriers offer full, immediate coverage even for applicants managing conditions like controlled diabetes or high blood pressure.
How Much Does Final Expense Insurance Cost?
Premiums for insurance final expense plans depend on four main variables: your age, your gender (men generally pay more due to shorter average life expectancy), your desired coverage amount, and your health history.
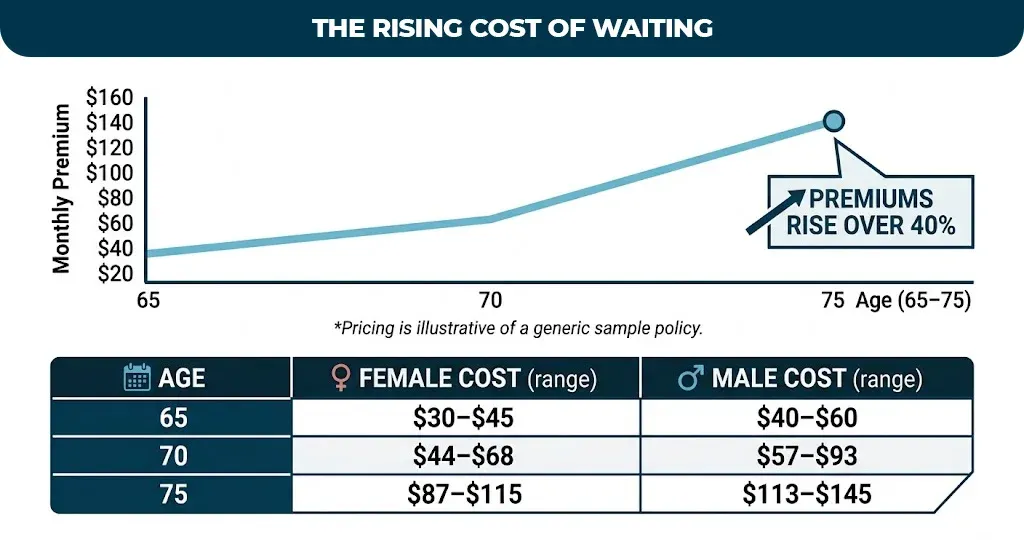
Below are sample monthly premium ranges for $10,000 in simplified issue coverage one of the most common configurations seniors search for when comparing cheap life insurance for seniors:
| Age | Females (monthly) | Males (monthly) |
| Age 65 | $30 – $45 | $40 – $60 |
| Age 70 | $44 – $68 | $57 – $93 |
| Age 75 | $87 – $115 | $113 – $145 |
The pattern is clear: waiting costs money. Premiums often jump more than 40% between ages 70 and 80, since insurers price a policy based on your age at application, not your age when you eventually pass away. Locking in a rate in your mid-60s instead of your mid-70s can mean paying tens of thousands of dollars less over the life of the policy for the same $10,000–$25,000 death benefit.
How to Choose the Right Policy: Step-by-Step
- Calculate your true need. Add up expected funeral costs (using NFDA benchmarks as a baseline) plus a $2,000–$5,000 buffer for lingering medical bills or debt.
- Apply for a simplified issue first. Don’t assume guaranteed issue is your only option; many seniors with well-managed chronic conditions still qualify for lower-cost, day-one coverage.
- Work with an independent broker. An independent agent can compare quotes across several top-rated carriers instead of pushing a single company’s product.
- Review the fine print. Confirm the payout timeline, understand how cash value accrues, and always name a contingent beneficiary in case your primary beneficiary passes before you do.
Conclusion
Planning ahead for end-of-life expenses is one of the most practical gifts you can give the people you love. A final expense insurance policy means that when the time comes, your family can focus on saying goodbye instead of adding up funeral home invoices. Because rates only increase with age, the smartest move is securing coverage today rather than waiting another year.
Ready to compare instant quotes from top-rated carriers? Visit Insure Final Expense to see day-one coverage options, side-by-side pricing, and licensed specialists who can match you with a final expense program built around your health and your budget all with no medical exam required. Get your free, no-obligation quote today.
Expert Final Expense & Life Insurance Agent
Steffanie is a licensed life insurance specialist at Insure Final Expense, focusing on final expense, burial, and senior life insurance solutions. With years of industry experience, she helps families secure affordable coverage designed to protect their loved ones from financial hardship. Her content is carefully researched, compliance-focused, and created to provide clear, trustworthy guidance so readers can make confident insurance decisions.